SPV: what is it and what is it for?
In corporate finance, having mechanisms that allow risks to be properly managed, investments to be optimised and complex transactions to be facilitated is crucial. One of the most prominent tools for achieving these objectives is the Special Purpose Vehicle (SPV). Below we explore exactly what an SPV is, why it matters, and how it is used to structure investments, protect assets and manage advanced financial transactions.
Special Purpose Vehicles (SPVs) have become key financial tools for structuring complex transactions in the modern business world. These separate legal entities make it possible to isolate risks, attract financing and execute specific projects without compromising the financial health of the core business. Below we set out what SPVs are, how they differ from traditional companies, their strategic uses, advantages, risks, formation process, practical examples and recommendations for their implementation, always highlighting the importance of expert advice.
A Special Purpose Vehicle (SPV), also known as a special purpose entity, is an independent legal entity created for a specific purpose and with a limited lifespan. Unlike a conventional operating company, an SPV does not pursue a broad corporate purpose; it is set up to execute a specific transaction or project, with its own balance sheet, assets and liabilities, and a legal personality separate from the sponsoring company.
In essence, the SPV acts as a "vehicle company" whose purpose is to encapsulate certain assets, investments or activities, so that if the parent company were to run into financial difficulties or even bankruptcy, the SPV can continue operating without being directly affected. This "bankruptcy-remote" characteristic means that the obligations and risks associated with the specific project are contained within the SPV, protecting the sponsor from direct impacts on its consolidated balance sheet.
In practice, an SPV can take various legal forms. What is essential is that the SPV has a strictly delimited activity and corporate purpose: it does not carry out general commercial operations, only those related to its special purpose. Thanks to this design, SPVs are used to isolate specific financial risks, directly secure the ownership of a particular asset, or channel investment into a project, without any of this affecting the rest of the group's operations.
Differences between an SPV and a traditional company
Although an SPV is formally a company (it has its own legal personality), it differs substantially from a traditional company in its purpose, operational scope and time horizon. The key differences are set out below:
- Purpose and scope: A conventional company usually has a broad corporate purpose and may cover multiple lines of business on an ongoing basis. By contrast, an SPV is created with a specific, limited purpose: to execute a particular project, carry out a one-off transaction or hold certain assets in isolation.
- Legal and accounting independence: SPVs enjoy legal and accounting independence from their parent company or sponsor. This means that their financial statements, provided certain criteria are met, are not consolidated with those of the group, keeping the debts and assets of the special project separate. In a traditional company (for example, a wholly owned subsidiary of the parent), results normally are consolidated. To achieve this isolation, the SPV is often not directly owned by the sponsoring company.
- Duration of the entity: Traditional operating companies are generally conceived with a vocation of indefinite permanence. By contrast, an SPV is usually temporary, its life being tied to the duration of the project or the achievement of the objective for which it was created. The articles of association may stipulate that the SPV will be wound up at the end of the project (for example, once the bonds issued have been repaid or the sale of an asset completed). Its life cycle is thus finite and predefined, unlike an ordinary company that seeks continuity in the market.
- Activity and resources: A traditional company carries out commercial activities, has employees and infrastructure, generates revenue from multiple sources, and so on. By contrast, an SPV typically has no ordinary commercial activity or significant workforce of its own. It is common for the SPV to outsource the administration of its assets or for the sponsor to provide the know-how and appoint managers for the specific operation, but without involving the SPV directly in other businesses. For this reason, the operating costs of an SPV are usually low, and its management is limited to fulfilling the contracts and obligations of the special project.
In summary, while a traditional company seeks to create long-term value across various activities, an SPV is a focused vehicle, with a defined lifespan and a highly delimited scope based on a specific financial or investment objective. Understanding these differences is essential in deciding which structure to use in each case, whether to continue with the usual corporate structure or to isolate certain operations in an independent SPV.
What is an SPV used for in the financial world?
The main use of SPVs is linked to complex financial transactions that require risks to be isolated or specific assets to be managed efficiently.
1. Asset securitisation
Financial institutions transfer portfolios of assets (mortgages, consumer loans, leasing) to an SPV, which issues bonds backed by those assets. This mechanism makes it possible to convert illiquid assets into tradable instruments. Example: a bank securitises mortgages through an SPV, transferring credit risk and obtaining liquidity without compromising its solvency ratio. Securitisation and bond issues are, ultimately, essential routes for structuring corporate financing transactions as an alternative to traditional banking.
2. Project finance
In infrastructure, energy or transport projects, investment is channelled through SPVs, which sign the key contracts (contractors, suppliers, regulators) and take on the financing. Example: a solar plant financed via an SPV by a consortium of companies and institutional investors, with repayment linked to the project's cash flows.
The SPV is precisely the heart of every project finance transaction, where it encapsulates the project and makes risk isolation (ring-fencing) a reality.
3. Mergers and acquisitions (M&A)
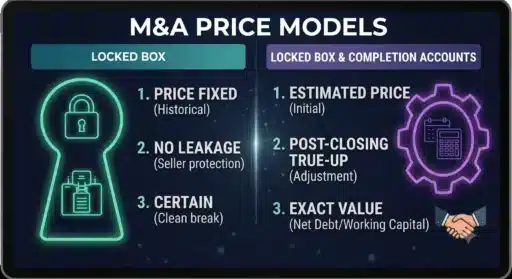
In certain acquisitions, especially leveraged ones (LBOs) or where the aim is to isolate the target's liabilities, SPVs are used as investment vehicles in mergers and acquisitions. For example, an acquiring company may set up an SPV (NewCo) that raises financing to buy a target company, with the acquisition debt confined to the SPV together with the assets of the acquired company.
This benefits the financial and risk structure of the transaction, since the parent company does not directly take on the debt or pledge its other assets as security. This use of the SPV (the NewCo) is characteristic of private equity and leveraged buy-out (LBO) transactions. The SPV can also facilitate integration, since it allows the target to be absorbed as a subsidiary of this intermediate entity. In mergers, temporary SPVs are also used to execute specific business combinations before merging them definitively with the parent, preserving certain tax or regulatory benefits.
4. Risk segregation
Companies transfer assets, liabilities or businesses with a high risk profile (litigation, volatility, sector concentration) to an SPV in order to protect the main balance sheet and preserve credit ratings. This makes it possible to manage any contingencies in isolation. In situations of difficulty, isolating a business or assets in an SPV can form part of a broader debt restructuring or refinancing strategy.
SPVs facilitate financing transactions, joint investments, mergers and acquisitions, allowing companies to manage specific risks or attract investors under clear, well-defined conditions.
How an SPV is created, step by step
The process of creating an SPV is relatively straightforward, although it requires careful attention to certain legal and tax aspects:
- Defining the objective: Delimit the activity, duration and specific purpose of the SPV.
- Choosing the jurisdiction and legal form: Select the appropriate country and corporate type according to tax, regulatory and operational factors.
- Legal incorporation: Registration with the Commercial Registry, articles of association, appointment of directors and formal compliance.
- Capital structure: Design of the combination of equity, senior debt, subordinated or mezzanine debt.
- Transfer of assets: Legal formalisation of the transfer of the assets or contracts needed for the SPV to operate.
- Governance and compliance: Design of control mechanisms, periodic reporting, audits and tax obligations.
- Planned dissolution: Establish criteria for winding up the SPV once its objective is achieved or after a set period.
Usual legal structure
An SPV generally takes legal forms such as a private limited company or a simplified public limited company, which guarantee limited liability and flexibility in management.
Advantages and risks of using an SPV
SPVs offer clear advantages, although they also carry certain risks:
Advantages
- Risk isolation: The failure of the project or deterioration of the asset affects only the SPV, without contaminating the parent company.
- Attracting investors: The separate structure offers legal certainty and traceability, facilitating co-investment.
- Tax optimisation: Use of efficient corporate structures and jurisdictions within the legal framework.
- Financial flexibility: The ability to issue debt or equity without compromising the main corporate structure.
- Transparency and traceability: Clear recording of flows and the project's individual performance.
- Speed of execution: Faster design and launch of specific transactions, without disrupting overall operations.
Risks
- Structural complexity: SPVs with multiple layers or cross-flows can hinder transparency.
- Legal and regulatory risk: Regulatory changes may force the SPV to be consolidated or taxed unexpectedly.
- Reputational impact: Although legally independent, problems in an SPV can damage the parent's image.
- Maintenance costs: Tax, legal and accounting obligations require ongoing management.
- Liquidity issues: Instruments issued by SPVs may have a thinner secondary market.
- Moral hazard and governance risk: Opaque or aggressive use of SPVs may be viewed negatively by regulators and stakeholders.
Practical SPV examples
- Bank A securitises €500M of mortgages through an SPV domiciled in Ireland. The SPV issues senior and mezzanine bonds. The bank offloads risk and improves its capital ratio.
- An energy consortium creates an SPV in Spain to build a 100 MW solar plant. It obtains financing through syndicated loans and guarantees from multilateral bodies. Revenue from the sale of energy repays the debt and distributes dividends.
- An industrial multinational establishes NewCo SPV in Luxembourg to acquire a competitor with structured debt. The parent maintains its financial profile and reserves the option of a future merger.
Is it advisable to use an SPV in your company?
The decision to use an SPV should be based on specific strategic considerations relating to the transaction or project in question.
It is advisable in the following cases:
- When external financing is sought for a specific project.
- When the aim is to limit the financial or legal exposure of the rest of the company.
- To facilitate the participation of institutional or strategic investors.
- In international transactions requiring legal or tax neutrality.
- When planning a securitisation or a reorganisation of assets.
- To create a joint venture with external partners under independent rules.
How a financial adviser can help you
SPVs allow companies to execute complex strategies with risk control, efficiency and access to capital. Their versatility makes them fundamental pieces of transactions such as securitisations, project financing, acquisitions or wealth management. However, their use demands responsibility, transparency and expert advice. Used well, SPVs are powerful tools for driving business growth without compromising the group's financial stability.
The complexity an SPV can involve makes professional financial advice crucial to its correct creation and management. Whether the SPV is used for an acquisition or sale (M&A), to finance a project or to reorganise the group structure, at Maraz Corporate Finance we can help you ensure that the SPV meets all legal requirements, optimises its operational and tax advantages, and is clearly aligned with your company's strategic objectives. In short, a well-structured SPV is a valuable strategic tool for companies seeking to maximise opportunities and manage financial and operational risks efficiently.
Javier de Rojas Roca de Togores
Partner – Maraz Corporate Finance
Frequently asked questions about SPVs
What exactly is an SPV?
It is an independent legal entity (Special Purpose Vehicle) created for a specific purpose and with a limited lifespan: to execute a project or a transaction, or to isolate certain assets. It has its own balance sheet and legal personality, and it is designed so that the project's risks do not contaminate the parent company (it is a "bankruptcy-remote" entity).
What is an SPV used for in a company acquisition (M&A)?
In leveraged acquisitions, an SPV (NewCo) is created that takes on the financing and buys the target company, so that the debt is confined to the SPV and does not compromise the buyer's other assets. It is a typical structure in private equity and LBOs, and a common tool in any M&A transaction.
How does the SPV relate to project finance?
It is its central piece. In project finance, the project is encapsulated in an SPV that signs the contracts, takes on the financing and repays it with the cash flows it generates. That way risk is isolated (ring-fencing) and the banks lend to the project, not to the sponsoring group.
Can an SPV be used to take debt off the balance sheet?
It can help isolate debt and risks, but with caution: under current accounting standards (control criterion, as in IFRS 10), if the company controls the SPV it must consolidate it, whatever label it carries. The real benefit is not cosmetic but substantive: the isolation of risk and the absence of full recourse against the sponsor. Opaque use can bring regulatory and reputational risks.
When is it advisable to set up an SPV?
When financing is sought for a specific project, when the aim is to limit the legal or financial exposure of the rest of the group, when co-investors need to be attracted, or when a securitisation or a joint venture is being planned. Securitisation and bond issues, for example, are alternative financing routes that are structured through SPVs.