M&A in Alicante:
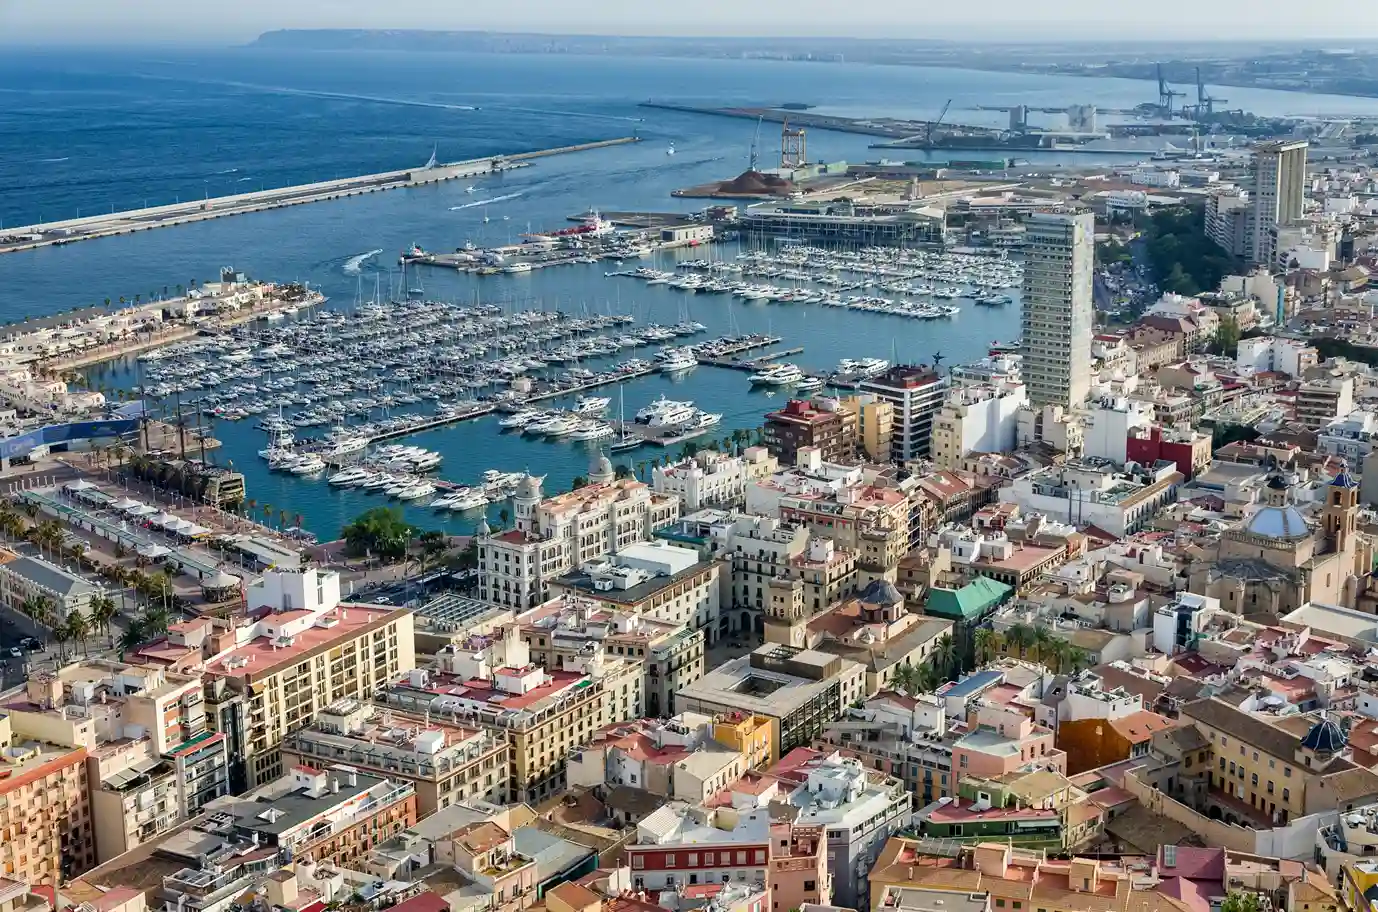
The province of Alicante is home to more than 145,000 active companies. It is the fourth most populous province in Spain, the fifth by GDP, and one of the most diversified economies of the Mediterranean arc. A dense, active business fabric with an entrepreneurial vocation — but with a structural problem that holds back its potential: size.
More than 95% of Alicante companies are micro-enterprises. This is not a statistical anecdote. It is the reason why many companies in the province, despite having competitive products, loyal customers and decades of experience, fail to make the leap they deserve. Size limits investment capacity, makes financing more expensive, hinders internationalisation and reduces bargaining power with customers and suppliers. In short, it squeezes margins and long-term growth.
Against this backdrop, inorganic growth through M&A transactions — mergers and acquisitions — represents one of the most effective strategies for overcoming these limitations. And the time to consider it has never been more opportune.
The structural challenge of Alicante's business fabric
Of the more than 145,000 active companies in the province, more than half have no employees. Barely 0.46% are medium-sized companies, and only 112 have more than 250 employees. The average size of an Alicante company is below even the national average, itself one of the smallest in Europe.
This fragmentation is not exclusive to Alicante. Spain is the European country with the highest proportion of SMEs, followed closely by Italy and Portugal. The average Spanish company employs fewer than five people, compared with six in the European average and almost twelve in Germany. Average turnover per company is a third lower than that of its European counterparts. And productivity per hour worked is equivalent to approximately three quarters of the eurozone average, a gap that has barely narrowed in two decades.
The consequences are concrete: less R&D capacity, greater dependence on bank credit, less international presence and less resilience to external shocks. In sectors such as footwear, marble or agri-food — historical pillars of the Alicante economy — this fragmentation is becoming a critical vulnerability against European and Asian competitors with greater scale.
Raising the average size of Spanish companies to the European level could increase national GDP by more than five percentage points and generate close to a million additional jobs. The message is clear: growing is not just a strategic option, it is a competitive necessity.

Companies per revenue in Alicante M&A | Maraz Corporate Finance
Why M&A in Alicante is the logical lever
Mergers and acquisitions allow a company to grow quickly and in a structured way, combining resources, capabilities and market share without relying exclusively on organic growth. The result, when well executed, generates what corporate finance calls synergies: the combined value exceeds the sum of the parts. It is not an abstract formula — it translates into lower operating costs, greater bargaining power and access to markets that would otherwise require years of development.
- Economies of scale and operational efficiency. Integrating two companies makes it possible to share infrastructure, teams and processes, reducing unit costs and improving profitability. It also opens access to financial, technological or R&D resources that would be inaccessible individually. For a ten-employee company that absorbs a competitor of similar size, the qualitative leap in management, systems and investment capacity can be transformative.
- Better access to financing. Larger companies negotiate better terms with financial institutions. They have greater capacity to offer security, a longer credit history and more diversified revenue. In practice, consolidation opens the door to financing instruments — corporate debt, working capital lines, leasing — that micro-enterprises simply cannot access on competitive terms.
- Greater bargaining power. A larger company negotiates better with suppliers, customers and financial institutions. That greater power translates directly into better margins and a more solid position for undertaking new acquisitions. In sectors such as food distribution or footwear, where large buyers dictate terms, size is not a luxury but a requirement for maintaining profitability.
- Accelerated internationalisation. Alicante's exports exceed €6.9 billion a year, with France, Germany and Italy as the main destinations. But most companies export irregularly and on tight margins. Acquiring a competitor with a presence in a foreign market allows entry from an already established position, without the costs and timescales of organic development. It is an effective way to diversify geographically and reduce dependence on a single channel or market — critical in an environment of growing tariff uncertainty.
- Succession and business continuity. This is perhaps the least visible but most relevant factor for Alicante's reality. The vast majority of companies in the province are family businesses, and the statistics are harsh: only one in three Spanish family businesses successfully survives the first generational handover. Two in three have no structured succession plan. In many cases, a sale to a third party, a merger with a strategic partner or the entry of private capital is the only real alternative for preserving what has been built over decades.
What is happening in M&A in Alicante
M&A is not an abstract trend or a phenomenon reserved for Madrid or Barcelona. In recent years, the province of Alicante has seen significant transactions demonstrating that international investor interest is real and growing.
Top-tier European funds have acquired Alicante companies that lead their sectors: from ice-cream manufacturers with more than 850 employees to assisted-reproduction clinics with an international presence, as well as photovoltaic self-consumption companies and childcare brands with distribution across Europe. Hotel investment in the province exceeded €120 million in 2025 alone, with international operators consolidating assets on the Costa Blanca. And in agri-food, concentration processes are advancing in citrus, turrón and wine, with companies that have made consolidation their main growth engine.
The Valencian Community closed 2025 with 85 M&A transactions and more than €1.4 billion of aggregate investment, becoming one of the most dynamic hubs of transactional activity in Spain. The most active sectors were technology, consumer, agri-food, industry and healthcare — all with a significant presence in the province of Alicante.
What matters is not just the figures. It is that this activity generates a knock-on effect: every company that is sold or merged sets valuation references, attracts new buyers to the sector and shows other business owners that the process is feasible.
Alicante sectors with the greatest consolidation potential
Some sectors in the province present especially favourable conditions for M&A transactions, whether as buyers, as sellers or as participants in mergers between equals.
Footwear in the Vinalopó concentrates the bulk of Spanish production, with Elche and Elda as its epicentres. The sector is going through a deep restructuring: falling exports, pressure from Asian competition and a fabric of mid-sized brands with market recognition but weak financial structures. Companies with greater scale and brand strength are positioned to lead a consolidation the sector urgently needs.
Marble from Novelda and the Vinalopó corridor accounts for approximately 70% of the marble exported by Spain. It is a sector with a global presence but highly fragmented in its processing link. Obtaining a Protected Geographical Indication can act as a catalyst for value and for concentration among the surviving operators.
Tourism and hospitality on the Costa Blanca are experiencing record investment, with 8 million foreign tourists in 2024 and an average room rate that leads the Valencian Community. Mid-sized family operators are on the radar of international funds seeking assets in established destinations with growing demand. The difference between an individually managed family hotel and one integrated into a chain with scale can mean decades of profitability.
Agri-food in the Vega Baja and the north of the province combines growing export volume — the sector overtook footwear for the first time as the province's leading export item — with a highly fragmented structure of producers and cooperatives. The vertical and horizontal integration processes taking place in citrus, horticulture and wine suggest that consolidation of the sector is an unstoppable trend.
The plastics and toy industry of the Foia de Castalla has shown a remarkable capacity for reinvention. The plastics industry has grown 44% in five years and exceeds €660 million in turnover, presenting favourable conditions for horizontal consolidation between complementary companies.
M&A in Alicante: a strategy within reach of Alicante companies
M&A is not exclusive to large corporations. The segment where the most active funds operate — companies with turnover of between €10 and €100 million — covers a good part of Alicante's leading business fabric. The right question is not whether to explore a transaction, but in which role — buyer, strategic partner or seller — you want to take part.
For those considering buying, the buy-and-build strategy — successive acquisitions to gain size — is the most structured route; it is also worth mastering the stages of the sale process from the buy side and the financial due diligence checklist so as not to take on hidden risks.
For those considering selling or bringing in capital, the preparatory work is decisive: it is worth knowing how to prepare the company for sale, how to increase its value before selling it and what taxes the sale of a company in Spain entails. And in any case, the starting point is always a rigorous business valuation.
At Maraz Corporate Finance we support companies in the province throughout the process: identifying opportunities, valuing the target business, approaching the owners, negotiation, due diligence and closing. We also advise owners considering a sale or the entry of capital, within our M&A transaction advisory service.
If you are considering growing through an acquisition, exploring a merger with a competitor or understanding what options your company has, contact our team and we will analyse it with no obligation.
Javier de Rojas Roca de Togores
Partner - Maraz Corporate Finance
Frequently asked questions about M&A in Alicante
Is an M&A transaction feasible for an Alicante SME, or only for large companies?
It is perfectly feasible. The most active segment of the market — companies with turnover of between €10 and €100 million — covers a good part of Alicante's leading business fabric, and national and international funds operate precisely in that range. Moreover, you do not need to be large to buy: many transactions consist of a mid-sized company absorbing a competitor of similar size to gain scale. The key is not size, but approaching the deal with advice and method.
Which sectors in Alicante have the most company sale and purchase activity?
The sectors with the greatest consolidation potential in the province are footwear in the Vinalopó (Elche and Elda), marble in Novelda, tourism and hospitality on the Costa Blanca, agri-food in the Vega Baja and the plastics and toy industry in the Foia de Castalla. The Valencian Community closed 2025 with 85 deals and more than €1.4 billion of investment, with technology, consumer, agri-food, industry and healthcare as the most dynamic areas.
My company is family-owned and I have no clear successor. Is M&A a solution?
Yes, and it is one of the most common reasons for starting a transaction in Alicante. Only one in three Spanish family businesses survives the first generational handover, and two in three have no structured succession plan. When there is no family continuity, a sale to a third party, a merger with a strategic partner or the entry of private capital make it possible to preserve the business, the jobs and the wealth built over decades, rather than letting the company deteriorate for lack of a successor.
How much is my company worth and how will I know before negotiating?
Value depends on the sector, size, recurrence of revenue and the buyer's profile. In the middle market, EBITDA multiples are usually used, which vary greatly by sector, combined with discounted cash flow for greater rigour. The essential thing is to have a professional, independent valuation before sitting down to negotiate: that is what allows the price to be defended with technical arguments against an experienced buyer, rather than accepting the first figure put on the table.
How long does an M&A transaction take and what are its phases?
A well-managed transaction usually takes between six and twelve months. The phases are: preparation and valuation, preparation of the sale documentation and search for counterparties, marketing and selection of the buyer, signing of the letter of intent, due diligence (the buyer's audit) and, finally, negotiation of the sale and purchase agreement and closing. Having an adviser coordinate the process shortens the timeline and, above all, prevents the deal from collapsing due to management or pacing errors.