Working capital is one of the fundamental pillars for guaranteeing the liquidity and financial stability of any company. In a dynamic and competitive business environment, managing financial resources correctly can make the difference between success and insolvency. This article explains what working capital is, how to calculate it and why it is essential for the financial health of your company.
If you are looking for the detailed technical definition and the distinction from net working capital, we develop it in our article on what working capital is and why it matters; here we focus on its impact on financial health and on how to improve it.
What is working capital and why is it essential for companies?
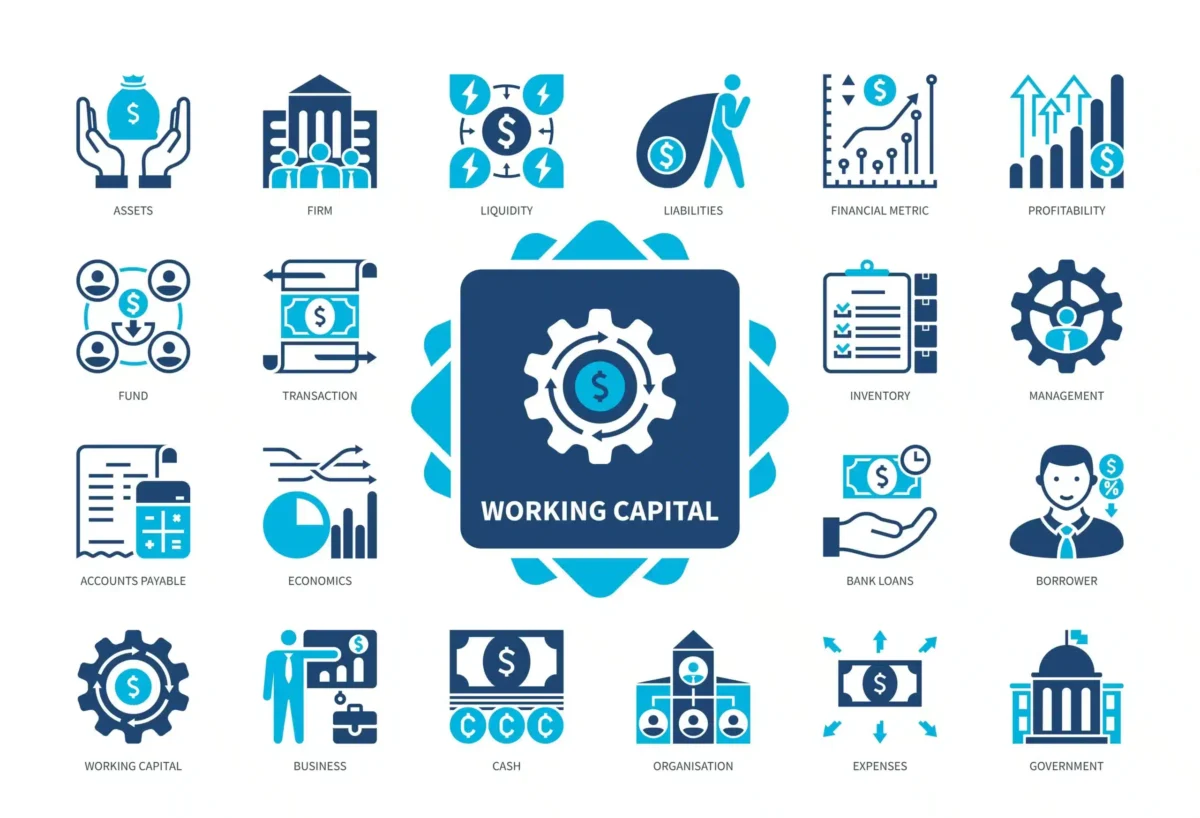
Working capital, also known as net working capital, refers to the financial resources needed to cover a company's day-to-day operations. Essentially, it is the difference between current assets (cash available, receivables, inventories) and current liabilities (short-term debts). Proper working capital management ensures that the company can meet its immediate obligations without putting its solvency at risk.
For example, if a company needs to buy raw materials to produce goods and sell them on credit, its working capital is crucial to financing the purchase before receiving payment from customers. Without adequate working capital, the company could find itself unable to meet its obligations, which would affect its ability to operate.
Difference between working capital and fixed capital
Unlike working capital, which relates to the resources used in the company's day-to-day running, fixed capital is made up of long-lived assets, such as property, machinery and equipment. Whereas working capital is used quickly and renewed frequently, fixed capital has a longer life cycle and is not devoted to daily operations.
The working capital formula and how to interpret it
The basic working capital formula is fairly simple:
Working Capital = Current Assets - Current Liabilities
- Current assets: those assets that can be converted into cash within less than a year, such as cash, receivables and inventories.
- Current liabilities: the debts and obligations that must be paid within one year, such as payables and short-term loans.
Operating working capital
It is important to distinguish operating working capital, which excludes cash and financial assets/liabilities, since these do not form part of the company's day-to-day operations. The formula would be:
Operating Working Capital = (Current Assets - Cash - Financial Assets) - (Current Liabilities - Financial Liabilities)
This adjustment offers a clearer view of the company's operating capacity to cover its short-term obligations without relying on financial assets that are not directly related to its core activity.
Worked example
Imagine a company with the following figures:
- Current assets: €500,000
- Current liabilities: €300,000
- Cash: €100,000
- Financial liabilities: €50,000
The formula would be:
Working Capital = €500,000 - €300,000 = €200,000
Operating Working Capital = (€500,000 - €100,000) - (€300,000 - €50,000) = €400,000 - €250,000 = €150,000
This means the company has €200,000 to cover its daily operations, but its operating working capital, which reflects the resources available for day-to-day activities, is €150,000.
The importance of working capital in financial management
Well-managed working capital has a direct impact on the company's daily operations and on its ability to take informed financial decisions.
Guaranteeing liquidity and daily operations
Working capital ensures that the company has sufficient liquidity to finance its daily operations without relying excessively on external credit. A key point is that a company can be profitable and have apparently ample working capital, but if a large part of that capital is tied up in inventories or long-dated receivables, it could face illiquidity. This means that, even though the company is profitable, it will not be able to meet its short-term payments because of poor working capital management.
That up-to-date view of cash is gained through good forecasting: a rolling forecast makes it possible to anticipate treasury strain before it occurs.
Capacity to meet short-term obligations
Working capital also allows companies to meet their short-term obligations, such as paying suppliers, salaries and other immediate debts. If working capital is negative or insufficient, the company could struggle to meet these commitments, which would affect its reputation and bargaining power, and might even require it to consider a debt refinancing to restore financial balance.
Strategies for optimising working capital
Optimising working capital is essential to maintaining financial stability and enabling the company to grow. Here are some key strategies:
Efficient inventory management
Proper inventory management helps reduce excess stock, which releases capital that can be used for other needs. Using advanced inventory management systems can improve this task. If there is no good integration between the sales/marketing department and the purchasing department, stock is likely to be badly sized, with excess inventory of certain references and lost sales due to stock-outs. It can also generate losses through expiry or obsolescence that force periodic write-downs of inventory. Optimising inventory management is key to good working capital management.
Better management of receivables and payables
Shortening the collection cycle and extending payment terms with suppliers can significantly improve working capital. Tools such as factoring and reverse factoring (confirming) are useful for speeding up collections and organising payments. It is essential to have a clear collections and payments policy to keep cash flow at adequate levels.
When collections need to be accelerated or working capital financed, tools such as factoring or reverse factoring — within the range of alternative financing — can turn receivables into immediate liquidity.
Use of financial and technological tools
The use of financial management software can help optimise control of receivables and payables, as well as facilitating decision-making based on real-time data. A properly designed Balanced Scorecard makes it possible to visualise the critical indicators and anticipate strain.
The impact of working capital on your company
Proper working capital management not only improves financial health, but also allows the company to grow with greater solidity and less risk. In addition, good working capital management has a direct impact on cash generation, which allows the company to reinvest in new assets or projects and increase its value in the market.
That cash generation is, in fact, one of the factors that most raise the value of a company and reduce its net debt. Efficient management of financial resources not only helps maintain solvency and liquidity, but also generates surplus cash, which opens up new investment opportunities.
If you would like a detailed analysis of how to improve your company's working capital, do not hesitate to consult our financial advisory or fractional CFO services, or to contact our experts for the preparation of financial reports. You may also be interested in our analysis of how to protect gross margin against rising costs.
Javier de Rojas Roca de Togores
Partner - Maraz Corporate Finance
Frequently asked questions about working capital
How is working capital calculated?
It is the difference between current assets (cash, receivables, inventories) and current liabilities (short-term debts). There is also operating working capital, which excludes cash and financial items to reflect only ordinary activity. We explain it in detail, together with the distinction from net working capital, in what is working capital.
Can a profitable company have liquidity problems?
Yes, and it is more frequent than it seems. A company can be profitable but have a large part of its capital tied up in inventories or in long-dated receivables, which prevents it from meeting its short-term payments. Profitability and liquidity are not the same: you can make money and still run out of cash.
How can I improve my company's working capital?
With three levers: manage inventory better (avoid excess and stock-outs), shorten the collection cycle and negotiate payment terms, and use tools such as factoring or reverse factoring from alternative financing. A fractional CFO diagnosis identifies where cash is trapped.
What is the difference between working capital and fixed capital?
Working capital is the resources used and renewed day to day (inventories, collections, short-term payments). Fixed capital is the long-lived assets (property, machinery, equipment) that are not devoted to daily operations and have a long life cycle.
How can cash strain be anticipated?
With forecasting. A rolling forecast updated monthly makes it possible to see in advance when working capital is going to put pressure on cash, so that action can be taken beforehand (adjusting collections and payments, sizing inventory or seeking financing) rather than reacting late.